
Qantas surprised us all today with the announcement that Jetstar Asia will be wound up in the coming months. We view this as a surprise, not because Jetstar Asia’s struggles aren’t well understood, rather because of Qantas’s steadfast support for Jetstar Asia in the aftermath of the COVID-19 pandemic.
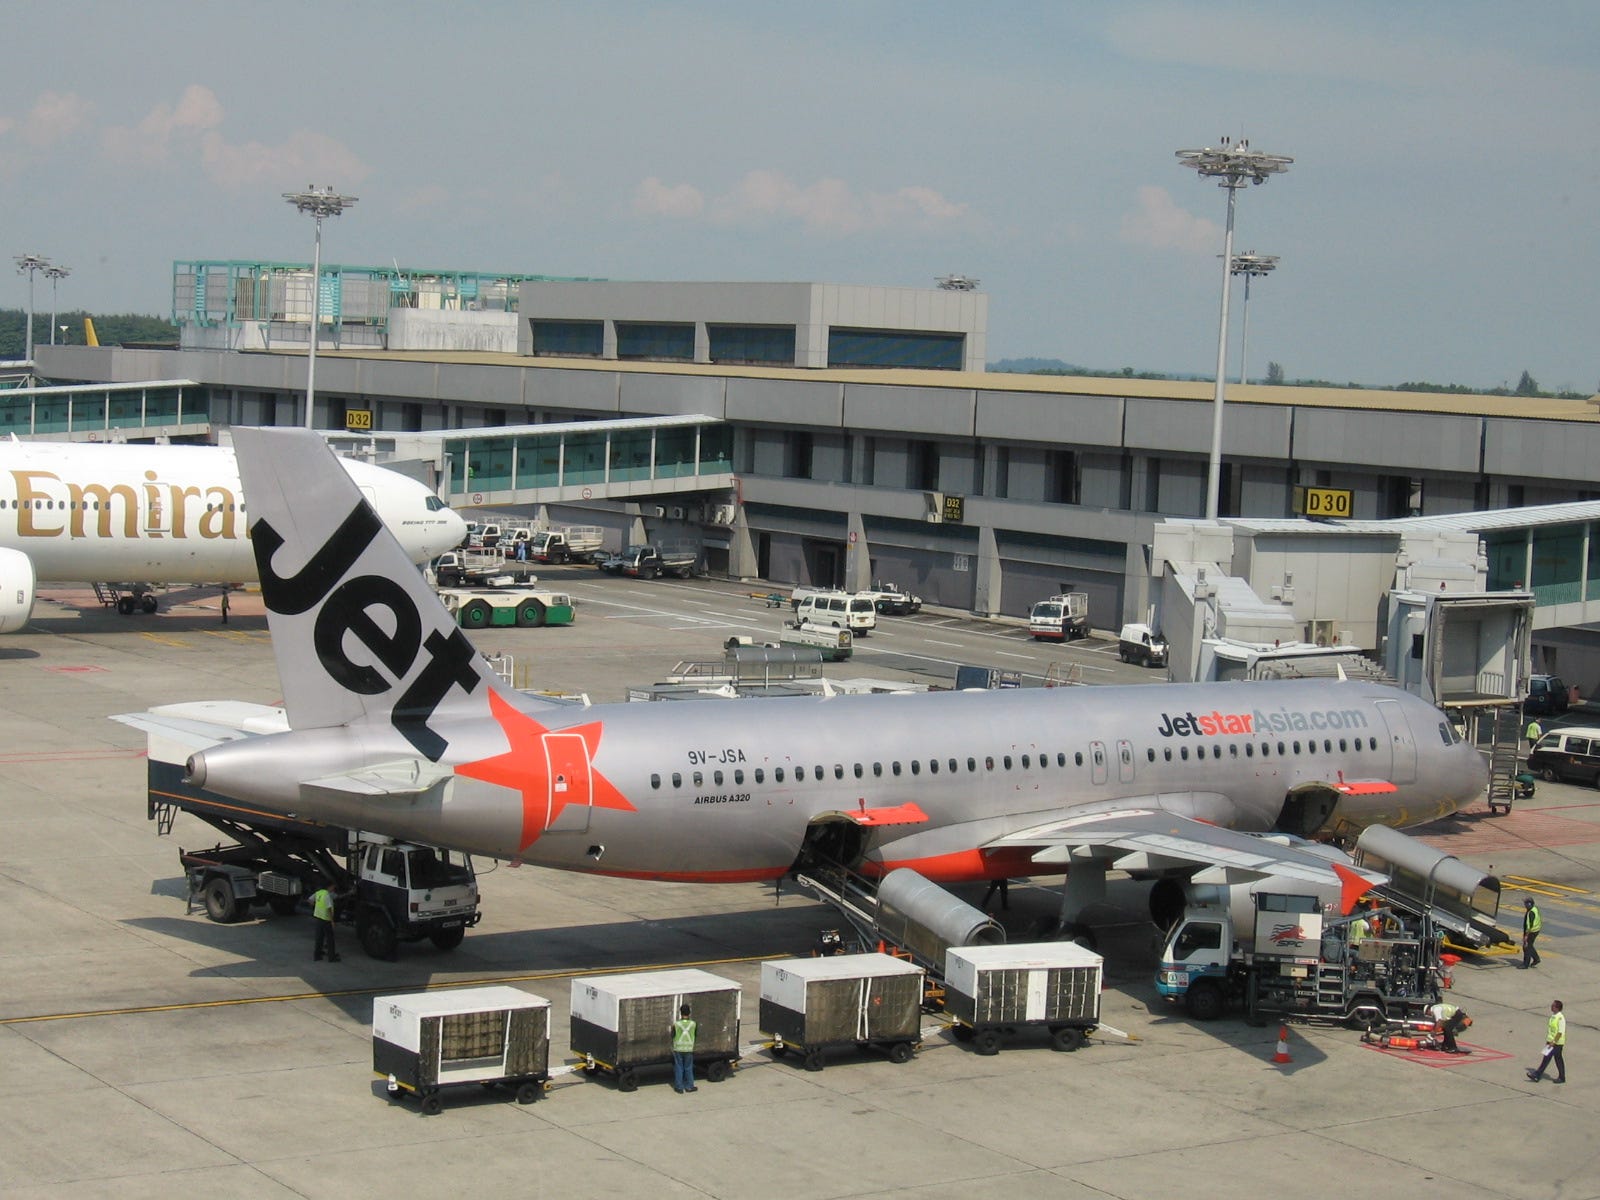
Despite it’s inability to find sustainable profitability during two decades of operations, Jetstar Asia played an important strategic role in the Qantas Group providing connectivity and redundancy capacity to several important SE Asian destinations. The loss of connectivity presents several immediate challenges for Qantas and Jetstar, and likely wasn’t a decision taken without due consideration.
While Qantas’s statement pins the decision squarely on financial performance, blaming rising supplier costs, high airport fees, and intensified competition in the region, these are somewhat superficial as these are challenges that have been tolerated for much of the last two decades.
We propose an alternative hypothesis: firstly, that Jetstar Asia no longer provides the same strategic benefit it once did or was intended to provide; secondly, that the network effects are being achieved through other means; and thirdly, that the opportunity cost of capital allocation has increased given the increased profitability of Jetstar’s domestic operations in Australia and continued supply side capacity constraints. Let’s consider …